
Risk-Off Sentiment Prevails
Key Takeaways
- Consumer spending remained a key driver of economic growth.
- Corporate earnings continue to surpass analyst expectations.
- Global stocks rallied despite softer-than-expected GDP growth.
The initial estimate of second quarter GDP was announced this week, and the result was lower than forecast with an initial reading of 1.5%. This compares to an expected level of 2.1%, which coincidentally was the level of growth achieved in the first quarter. Consumers continued to demonstrate their willingness to spend as their contribution registered an increase of 3.2% (annualized). Continued strength in business investment was also seen in the results. Offsetting these two positive factors was a decrease in government spending and a substantial increase in imports which actually reduces the level of GDP growth.
While the initial estimate of GDP growth was below consensus, The Federal Reserve Bank of Atlanta’s GDPnow estimate of third quarter growth stands at a level of 5.8%.
In addition to the GDPnow estimate, the ISM surveys of the manufacturing and service sectors of the economy continue to point to further growth as both registered results for July that were well above the level needed to point to ongoing expansion.
Equity investors continue to see companies reporting very strong earnings for the second quarter. According to FactSet, as of last Friday 61% of the companies comprising the Standard & Poor’s 500 Index had reported and of those reporting 86% had reported results in excess of forecasted levels. Combining reported results with the expected level for companies yet to report would yield overall second quarter growth of 47%.
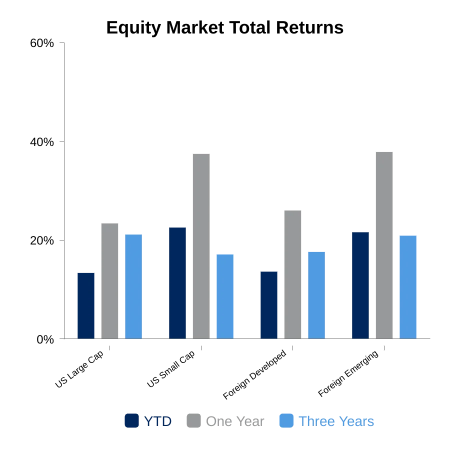
In addition to seeing impressive earnings results investors also saw impressive returns for the week. The domestic equity market return, as represented by the Russell 3000 Index, was up 3.8% for the week. Growth stocks were the primary driver, however value issues continue to lead on a year-to-date basis. Strong equity market performance was not exclusive to the U.S. last week as international markets also saw strong returns. Developed foreign markets, as measured by the MSCI EAFE Index, advanced 4.1% and emerging markets delivered an even stronger showing with a return of 8.2%.
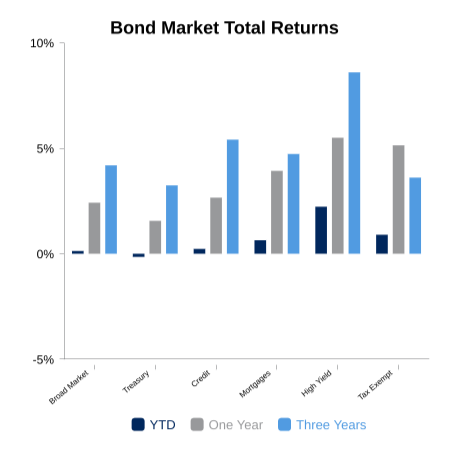
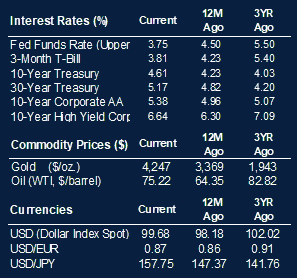
The fixed income markets also delivered positive returns with broad market indices rising by 0.5%. A decline in yields provided the positive momentum for this performance as the U.S. Treasury 10-year note yield fell to 4.61% from the previous week’s level of 4.68%. While a decline in rates was seen last week the increase that has occurred year-to-date has led to a return of essentially zero for the broad market indices from the beginning of the year.
 |
 |
Sources: BTC Capital Management, FactSet Research Systems, Inc., LSEG I/B/E/S, FTSE Russell (an LSEG Company), MSCI Inc. The Federal Reserve
The information provided has been obtained from sources deemed reliable, but BTC Capital Management and its affiliates cannot guarantee accuracy. Past performance is not a guarantee of future returns. Performance over periods exceeding 12 months has been annualized.
This content is provided for informational purposes only and is not intended as an offer or solicitation with respect to the purchase or sale of any security. Statements in this report are based on the views of BTC Capital Management and on information available at the time this report was prepared. Rates are subject to change based on market and/or other conditions without notice. This commentary contains no investment recommendations and should not be interpreted as investment, tax, legal, and/or financial planning advice. All investments involve risk, including the possible loss of principal. Investments are not FDIC insured and may lose value.