
Markets Mull Higher Oil Prices and Rising Yields
Key Takeaways
- Modest risk-on sentiment exhibits narrow leadership.
- Economic news – a mixed bag.
- Closing out a challenging quarter.
Modest risk-on sentiment exhibits narrow leadership
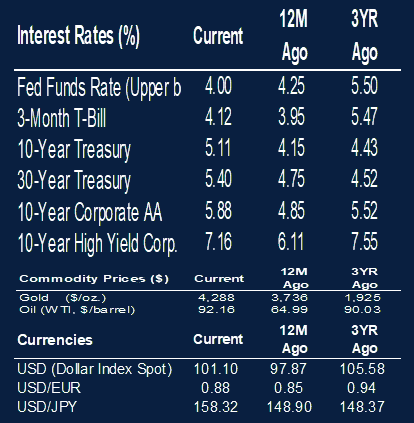
The week opened risk-off given a spike in oil prices coupled with the U.S. 10-year Treasury yield breeching 5.0%, the latter spurred by a Fed rate hike. As the week closed, sentiment reversed as oil prices retraced, while yields stayed firm.
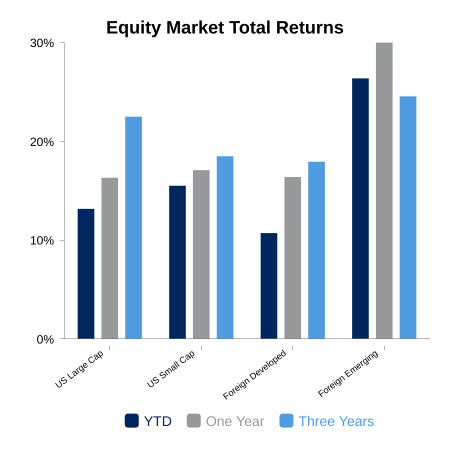
Equity markets navigated to a ”risk-on” sentiment, although overall breadth was narrow, specifically the divergence in the U.S. amongst large caps and small caps. The Russell 1000 Index rose 1.9%, driven by the Russell 1000 Growth Index, which surged 4.0%. According to MSCI, USA Momentum advanced 6.0% during this time. Analysis via the London Stock Exchange Group (LSEG) reveals a basket comprised of the Mag 7 companies rose 3.6%, outperforming the broader market. Conversely, small caps retraced, as the Russell 2000 Index declined 0.7%.
Emerging markets led over the course of this past week, as the MSCI Emerging Markets Index advanced 3.7%. According to MSCI, EM Momentum surged 7.7% for the week. The MSCI All-Country World Index ex-USA rose 0.7% for the week.
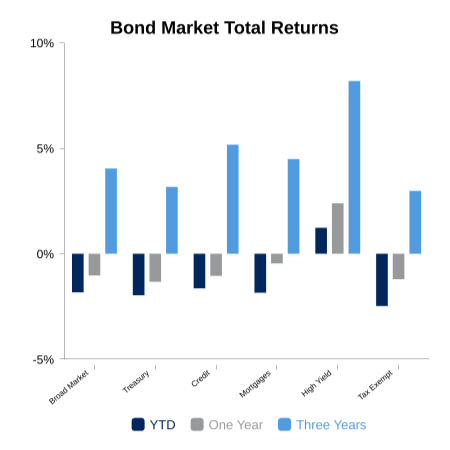
Bonds fell 0.4% for the week.
Economic news – a mixed bag
S&P Global released its Flash, or preliminary, Purchasing Manager’s Index (PMI) for September. According to S&P, “U.S. business activity growth accelerated for a fourth successive month in September to reach the fastest rate for over five years.” The Composite Index came in at 58.4, higher than consensus of 56.1 and August’s 56.0 (which was revised up from 53.9). PMI Services surged to 58.7 versus August’s 56.5, while PMI Manufacturing rose to 57.0 versus August’s 53.9, both driven by new orders with demand predominantly from within the U.S.
The Federal Reserve reported Industrial Production for August was unchanged. Manufacturing output decreased 0.3% during August, while construction fell 0.7%. Recall industrial production fell 0.2% in July.
The Conference Board released its Leading Economic Index (LEI) for August. LEI decreased 0.1%, its first decline since March, versus July’s increase of 0.2%. Four of 10 components measured declined relative to July, with “consumer expectations remaining a significant strain on the Index.”
Closing out a challenging quarter
Markets vacillated throughout this current quarter. Investors tackled numerous challenges given higher interest rates, a roiling energy market, and valuation concerns. One quarter remains in 2026, and soon we will be hearing from companies regarding third-quarter earnings and guidance. Stay tuned.
 |
 |
Sources: BTC Capital Management, FactSet Research Systems, Inc., London Stock Exchange Group plc, MSCI Inc., S&P Global, The Federal Reserve, The Conference Board.
The information provided has been obtained from sources deemed reliable, but BTC Capital Management and its affiliates cannot guarantee accuracy. Past performance is not a guarantee of future returns. Performance over periods exceeding 12 months has been annualized.
This content is provided for informational purposes only and is not intended as an offer or solicitation with respect to the purchase or sale of any security. Statements in this report are based on the views of BTC Capital Management and on information available at the time this report was prepared. Rates are subject to change based on market and/or other conditions without notice. This commentary contains no investment recommendations and should not be interpreted as investment, tax, legal, and/or financial planning advice. All investments involve risk, including the possible loss of principal. Investments are not FDIC insured and may lose value.