
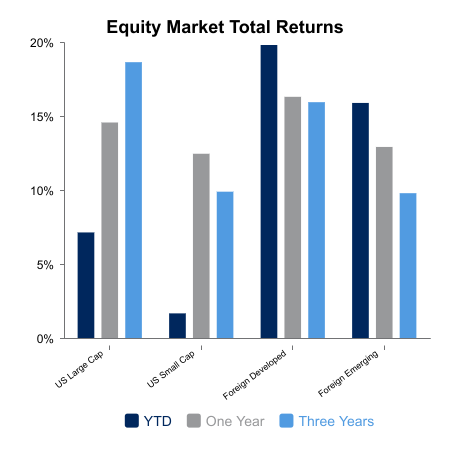
Equity markets rose modestly during the week as investors assessed new developments on the tariff front and mixed economic signals. The S&P 500 Index gained 0.6%, while the Nasdaq Composite rose 1.1%. The Magnificent 7 climbed 0.4%. Small caps climbed 0.8% for the week. Bond indices fell 0.2% during the week.
Tariff Deadline Extended
Investors awoke Monday morning after an extended holiday weekend to learn that the White House is expected to delay the implementation of new tariff rates until August 1. The new tariff rates were originally scheduled to begin in early July however the extended deadline was offered to allow other countries more time to negotiate trade deals with the U.S.
Additionally, on July 4, the “One Big Beautiful Bill” was passed by the House, extending the 2017 Tax Cuts, as well as increasing spending on border security and defense. The legislation also raised the debt ceiling by $5 trillion, higher than the original $4 trillion first proposed.
Economic Metrics Remains Mixed
Small business owners expressed concerns over excess inventories as the NFIB Small Business Optimism Index for June came in slightly lower than expected, and lower than May. The index remains higher than the 50-year average.
Overall, consumer credit rose less than forecasted for May, increasing to $5.1 trillion. Revolving credit, which is primarily credit card debt, decreased slightly during May as consumers moderated their spending during the month. Non-revolving credit, of which over 40% is student loans, increased during May.
Lowered Expectations for Second Quarter Earnings
Second quarter earnings season recently begun as investors await to see the early impact of tariffs and other market uncertainty. Current expectations for second quarter results are lower from a few months ago. In early April, expectations for year-over-year earnings growth for the second quarter were 10.2%. Currently, expectations for second quarter earnings growth are 5.8%. Sectors such as Energy and Healthcare have seen their earnings forecasts significantly reduced. The Communications Services and Technology sectors are forecasted to lead the market in earnings growth. Calendar year 2025 earnings growth is currently 8.4%, lower than earlier forecasts.
Foreign Markets Outpace U.S.
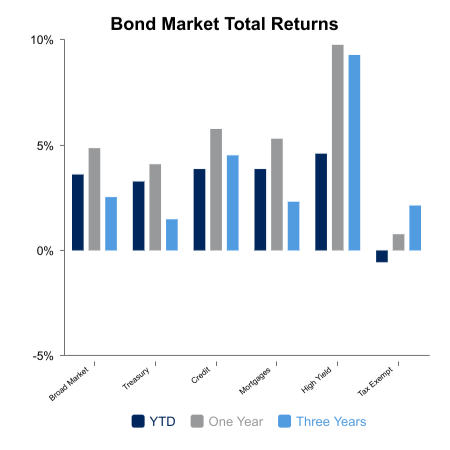
Foreign equity markets, both developed and emerging, continue to significantly outpace U.S. equity markets thus far, year-to-date. However, flows into global equity funds have slowed during the last few months, specifically in Western Europe where there had been significant inflows earlier in the year.
 |
 |
Sources: BTC Capital Management, FactSet Research Systems Inc., Federal Open Market Committee (Federal Reserve) LSEG I/B/E/S, FTSE Russell (an LSEG Group company), S&P Global, U.S. Bureau of Labor Statistics, U.S. Census Bureau
The information provided has been obtained from sources deemed reliable, but BTC Capital Management and its affiliates cannot guarantee accuracy. Past performance is not a guarantee of future returns. Performance over periods exceeding 12 months has been annualized.
This content is provided for informational purposes only and is not intended as an offer or solicitation with respect to the purchase or sale of any security. Statements in this report are based on the views of BTC Capital Management and on information available at the time this report was prepared. Rates are subject to change based on market and/or other conditions without notice. This commentary contains no investment recommendations and should not be interpreted as investment, tax, legal, and/or financial planning advice. All investments involve risk, including the possible loss of principal. Investments are not FDIC insured and may lose value.