
Risk Sentiment Swung from “AI Wobble” to Cautious Optimism During an Event-Heavy Week of Earnings Announcements and Economic Releases
Key Takeaways
- Positive news on the economic front.
- Strong third quarter earnings.
- Cautious optimism.
Positive News on the Economic Front
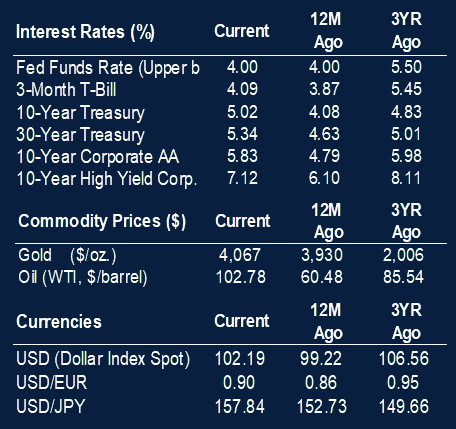
As anticipated, the Federal Open Market Committee (FOMC) announced its decision to maintain the Federal Funds target range at 3.75% to 4.00%, in the face of the upcoming mid-term elections. The FOMC acknowledged the economy continues to expand at a strong pace, supported by growth in productivity and robust capital investment.
The FOMC decision followed the release by S&P Global of its “flash” or preliminary, Purchasing Managers Index for October. According to S&P, growth in manufacturing and services expanded at the highest rate over the past five years supported by domestic demand and export growth, while employment increased at the second fastest pace over four years.
Closing out the positive sentiment was the Conference Board’s release of Consumer Confidence for October. The Board noted consumer confidence advanced as perceptions of current and expected business conditions improved. The Board tempered this rise noting consumer confidence continues in a downward trend “that’s persisted over the past few years.”
Strong Third Quarter Earnings
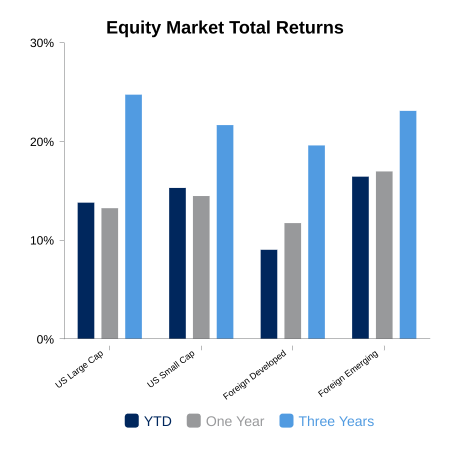
Growth in corporate profitability appears to have been robust during the third quarter. According to LSEG, 26.0% of the companies comprising the MSCI USA Investable Market Index (a broad measure of publicly traded domestic equities) have reported earnings grew 39.0% year-over-year (Y/Y). For companies yet to report, earnings growth is estimated at 28.9% Y/Y. Melding of these two metrics implies earnings grew 32.7% Y/Y during the third quarter.
Similarly, companies comprising the MSCI All-Country World Index ex-USA (a broad measure of both foreign developed and emerging markets) also exhibited vigorous growth. Approximately 28.7% of constituent companies have reported earnings grew 41.9% Y/Y, primarily driven by emerging markets. Earnings growth for companies yet to report is estimated at 39.1% Y/Y. Combining these two metrics implies earnings grew 39.8% Y/Y for the third quarter.
Cautious Optimism
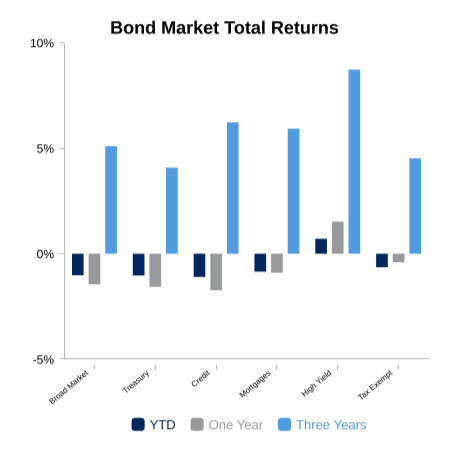
Yields fell over the week, which lifted the Bloomberg Aggregate Bond Index by 0.6%. Equities bounced off their lows given the positive economic and earnings reports but ended modestly lower. The Russell 3000 Index declined 0.1% while the MSCI All-Country World Index ex-USA fell 0.7%, primarily due to weakness in technology within South Korea.
November is around the corner and according to Bloomberg, has exhibited positive returns (on average) over the last five years.
 |
 |
Sources: BTC Capital Management, LSEG (London Stock Exchange Group), U.S. Federal Reserve, MSCI Inc., The Conference Board, S&P Global, Bloomberg LP
The information provided has been obtained from sources deemed reliable, but BTC Capital Management and its affiliates cannot guarantee accuracy. Past performance is not a guarantee of future returns. Performance over periods exceeding 12 months has been annualized.
This content is provided for informational purposes only and is not intended as an offer or solicitation with respect to the purchase or sale of any security. Statements in this report are based on the views of BTC Capital Management and on information available at the time this report was prepared. Rates are subject to change based on market and/or other conditions without notice. This commentary contains no investment recommendations and should not be interpreted as investment, tax, legal, and/or financial planning advice. All investments involve risk, including the possible loss of principal. Investments are not FDIC insured and may lose value.