
Can Earnings Season Surpass Elevated Expectations?
Key Takeaways
- Earnings season starts with strong results.
- Treasury yields pull back.
- Economic data remains strong.
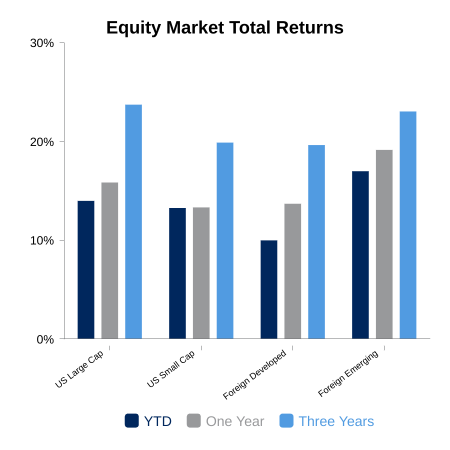
The S&P 500 was up 0.5% for the week and sits near an all-time high. The index is faring much better than the average stock. More than one-third of the S&P 500 constituents are more than 20% below their 52-week high. Despite this, the Index is less than 1% off its high. Semiconductors have been under pressure and are taking another leg lower today. This has also been a headwind to emerging markets, which fell 2.6% for the week. The rotation trade continues to be in play instead of wholesale selling across all industries. The energy sector remained the contra trade to semiconductors and was positive for the week.
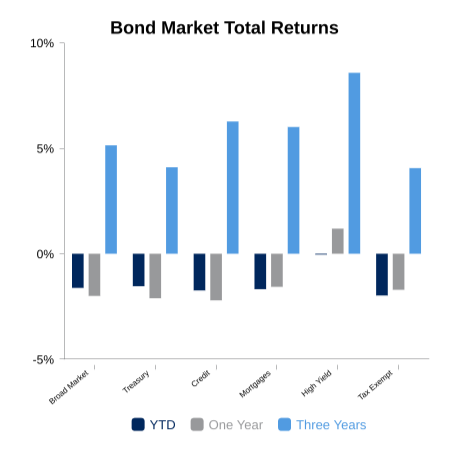
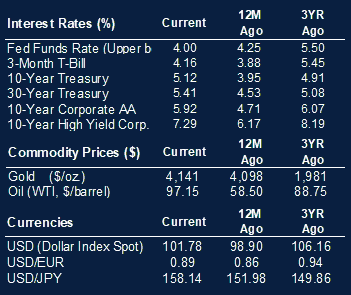
Core bonds were positive this week. Treasury yields have come off their high and appear poised to track the AI narrative in the short-term. Potential weakness in the AI outlook is thought to moderate some of the robust economic growth. Corporate bond spreads have now pushed out to their widest level since April. The 10-year Treasury yield has fallen 30 basis points over the last 10 trading days.
Third quarter earnings are underway with more than 10% of the Russell 1000 reporting thus far. Results have been solid with every sector demonstrating a positive earnings surprise, as well as positive earnings growth. Reported earnings growth thus far is up 30%. Despite this, post-earnings stock reactions have been evenly split between up and down.
Economic data comes in strong
Economic data came in better than expected this week. Retail sales beat the consensus on the headline number but were in-line when backing out autos and gas. While job growth has been relatively weak over the last two years, jobless claims tell a completely different story. We have gone six consecutive weeks with jobless claims at 200,000 or lower. The last time this occurred was in 1969 when the U.S. population was about 40% lower.
Inflation-related numbers were on the high side. Producer prices came in well above expectations. Import prices were up a robust 8.1% versus the prior year. Import prices have accelerated this year.
The Economic Leading Index from the Conference Board has been negative for more than four consecutive years, yet nominal GDP hit a four-year high. This indicator certainly missed something with the sharp drop in 2022, but it has been rising steadily for three years. And now this year it is showing sharp acceleration.
 |
 |
Sources: BTC Capital Management, Bloomberg
The information provided has been obtained from sources deemed reliable, but BTC Capital Management and its affiliates cannot guarantee accuracy. Past performance is not a guarantee of future returns. Performance over periods exceeding 12 months has been annualized.
This content is provided for informational purposes only and is not intended as an offer or solicitation with respect to the purchase or sale of any security. Statements in this report are based on the views of BTC Capital Management and on information available at the time this report was prepared. Rates are subject to change based on market and/or other conditions without notice. This commentary contains no investment recommendations and should not be interpreted as investment, tax, legal, and/or financial planning advice. All investments involve risk, including the possible loss of principal. Investments are not FDIC insured and may lose value.