
Election Results put the AI Trade on the Backfoot
Key Takeaways
- Technology shares slip.
- Inflation comes in hotter than expected.
- Economic data remains strong.
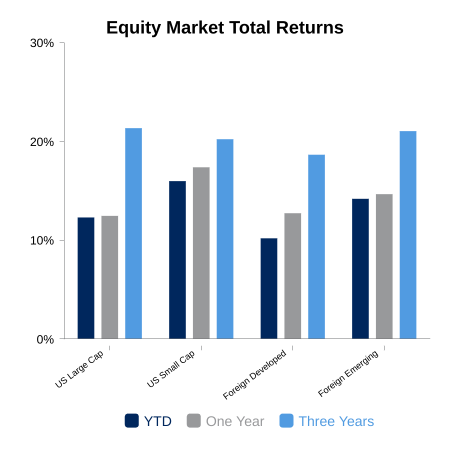
The S&P 500 was down 0.9% on the week, having clawed back most of the 4% drop that occurred last Thursday. Equity markets have moved lower following election results, led by declines in AI-related names. Several states with heavy dependence on AI had outcomes that raised the possibility of more regulation or a deceleration in the AI buildout.
Small caps fared better with more muted declines while foreign equities were outperformers on the week. Emerging markets and small caps separated from the pack mid-year, but recent pullbacks leave major markets more bunched up with a couple weeks remaining in the year. Most major market indices have year-to-date returns in the 10-15% range.
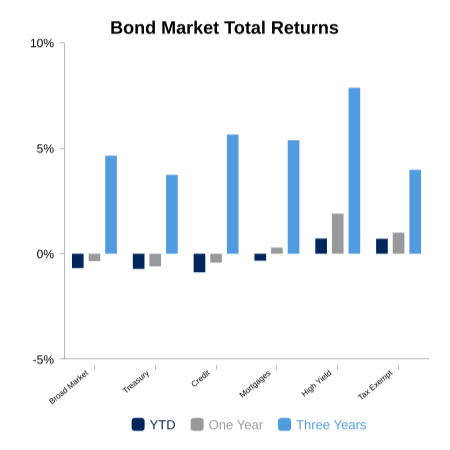
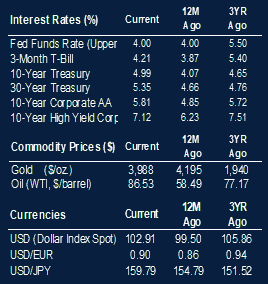
Core bonds were down on the week following strong gains in the month of October. Yields moved higher when the CPI report came in hotter than expected. Several Fed officials have commented this week that more action might be needed when it comes to interest rate increases. The market is currently pricing in more than a 25-bps increase at the December meeting. There is a possibility of a 50-bps increase based on Fed comments.
Economic data comes in strong
Economic data came in better than expected this week. Jobless claims continue to be exceptionally low with numbers down to 189,000 this week. Nonfarm payrolls on Friday came in well above expectations. The consensus was looking for 70,000 net gains and the result was 165,000. Revisions are often scrutinized to throw caution on the headline number. In this case, it added to the strength with net two-month revision of +84,000. The Citi Surprise Index has been making a vertical move over the last three months to now reach a three-year high. It is now poised to set the record for the most consecutive days over zero in the 23-year series history.
Inflation readings tracked the growth readings higher. Both core and headline CPI came in slightly higher than expected. Core CPI was up 0.3% versus the previous month for the third consecutive reading. This annualizes out to 3.6% inflation whereas 0.2% monthly increases yield a 2.4% inflation number. Fed Governor Christopher Waller was vocal that a 50-bps hike is worth consideration, which is a big pivot from the “wait and see” approach he supported heading into the October meeting.
 |
 |
Sources: BTC Capital Management, Bloomberg
The information provided has been obtained from sources deemed reliable, but BTC Capital Management and its affiliates cannot guarantee accuracy. Past performance is not a guarantee of future returns. Performance over periods exceeding 12 months has been annualized.
This content is provided for informational purposes only and is not intended as an offer or solicitation with respect to the purchase or sale of any security. Statements in this report are based on the views of BTC Capital Management and on information available at the time this report was prepared. Rates are subject to change based on market and/or other conditions without notice. This commentary contains no investment recommendations and should not be interpreted as investment, tax, legal, and/or financial planning advice. All investments involve risk, including the possible loss of principal. Investments are not FDIC insured and may lose value.